Key facts
- Kazakhstan and Uzbekistan are emerging as key players in tungsten supply, challenging China's dominance.
- Tungsten is critical for defense, aerospace, and chipmaking industries.
- China accounted for over 80% of global mine output in 2024.
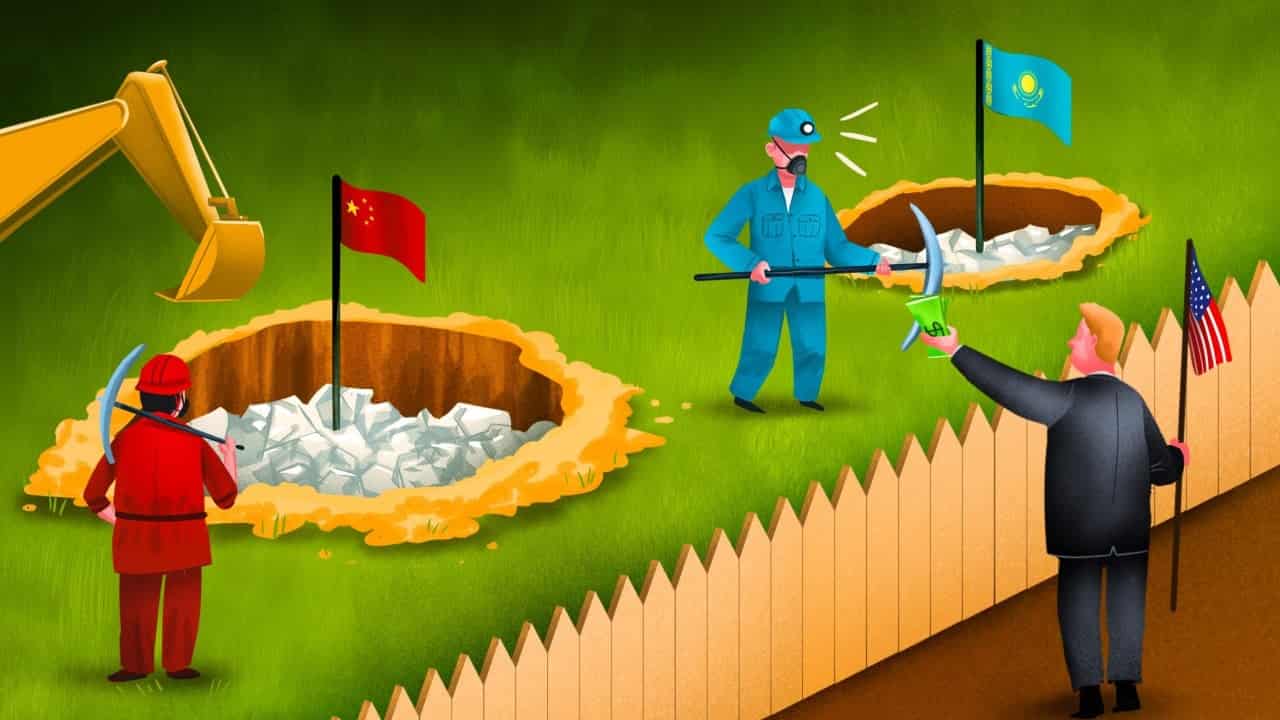
- US-backed projects are advancing in Kazakhstan, while Chinese-backed projects are also active.
- Ammonium paratungstate (APT) prices in China have risen over 200% since January 8, 2025.
The global tungsten market is undergoing a significant shift as the United States and its allies seek to reduce reliance on China, which has long dominated production. New mining projects in Kazakhstan, supported by US government funding, are aiming to compete with established Chinese operations.
Global tungsten prices have seen a dramatic increase, surging over 200% since May 2025, according to Argus Media. This price rally is attributed to China's implementation of export controls on certain tungsten products, prompting Western defense and industrial buyers to renew stockpiling efforts. Fastmarkets reported that the export APT price in China more than doubled from January 8, 2025, to $1,138-1,200 per metric tonne unit by January 14.
Tungsten's strategic importance stems from its indispensability in cutting tools, aerospace alloys, defense systems, and increasingly, chipmaking processes. NATO recognized this by designating tungsten as one of 12 "defense-critical raw materials" in December 2024. The US government also classified tungsten as a "highest risk" mineral on its draft list of Critical Minerals for 2025.
Central Asia, particularly Kazakhstan and Uzbekistan, is becoming a focal point for these efforts due to its substantial mineral reserves and supportive policies. In Kazakhstan, a US-backed joint venture aims to develop two undeveloped tungsten deposits, while a Chinese-backed producer has already operationalized the Bakuta open-pit mine. Uzbekistan is also fast-tracking projects and local processing capacity. The US Geological Survey noted that China accounted for over 80% of global mine output in 2024, with the US having not mined tungsten domestically since 2015.