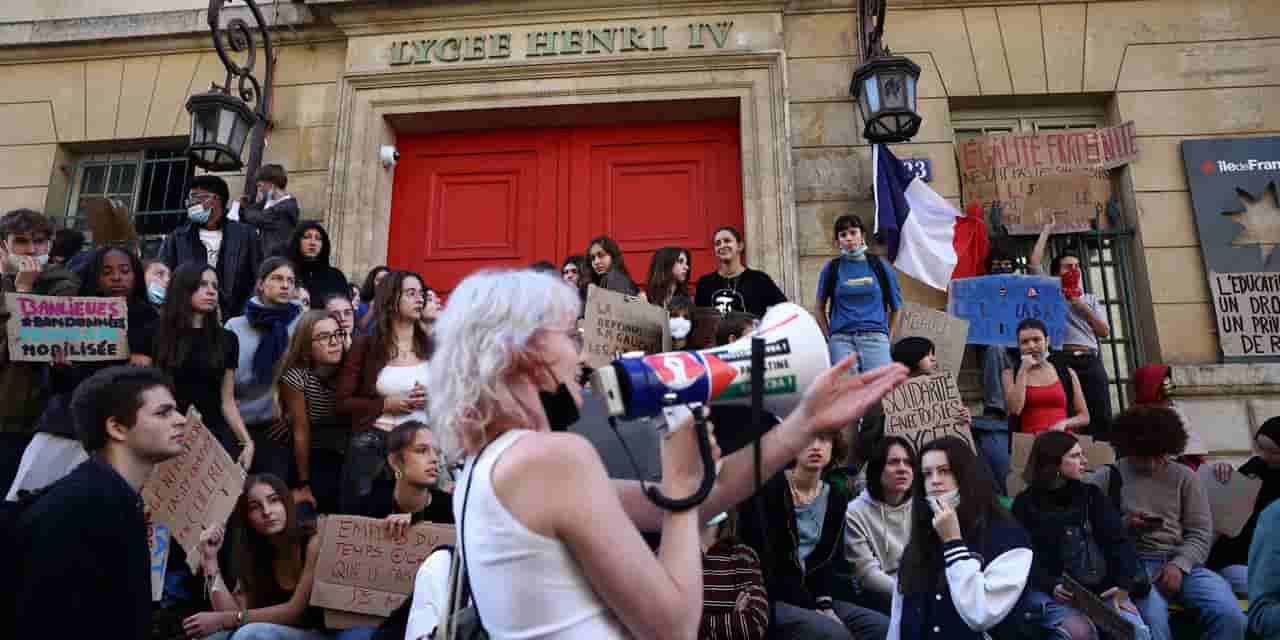
Key facts
- France's budget deficit is a growing concern for European markets.
- Rising borrowing costs are increasing the expense of servicing France's debt.
- The French government proposed a €54 billion savings program.
- Proposed savings include reductions in pension spending and government department funding.
- Defence spending was excluded from proposed savings.
- Strikes and protests are occurring in France due to proposed spending cuts.
France's public finances are under increasing scrutiny as its budget deficit widens and borrowing costs rise, sparking fears of contagion across the eurozone. The euro has fallen below $1.12 against the dollar, its lowest point since May 2025, and the spread between French and German 10-year bond yields has widened to its highest level since 2012, indicating that investors are demanding a higher risk premium for holding French debt.
This widening gap in borrowing costs creates a challenging cycle, as higher interest payments on existing debt can further strain public finances and complicate deficit reduction efforts. The French government has proposed a €54 billion savings program, including cuts to pension spending and government departments, to bring the deficit down from an estimated 5.5% of GDP this year to 5% next year. However, Prime Minister Ssbastien Lecornu has warned that without further measures, the deficit could reach 6.5%.
Cutting spending has become politically difficult for President Emmanuel Macron's government, which is facing strikes and protests. Political divisions in parliament also hinder fiscal consolidation efforts. These fiscal challenges are becoming increasingly significant ahead of France's next presidential election.
Analysts suggest that a sustained rise in French borrowing costs could have ripple effects throughout the eurozone, potentially leading markets to reassess the debt positions of other heavily indebted countries. While the European Central Bank possesses stronger tools than during the early 2010s sovereign debt crisis, markets remain sensitive to fiscal stress spreading through sovereign bond markets. UniCredit currency strategist Roberto Mialich noted that rising political tensions in France and Spain, coupled with contagion fears, are pressuring the euro.