Key facts
- Bill Collins made $12,656 sports betting in August, a gain of over 8%.
- Collins aims for a 3%-5% daily compound return on his sports bets.
- Over half of Gen Z investors have redirected funds into sports betting platforms.
- 26% of Gen Z investors view sports betting as a long-term investment strategy.
- The US sports betting industry is valued at $17 billion, up from $400 million in 2018.
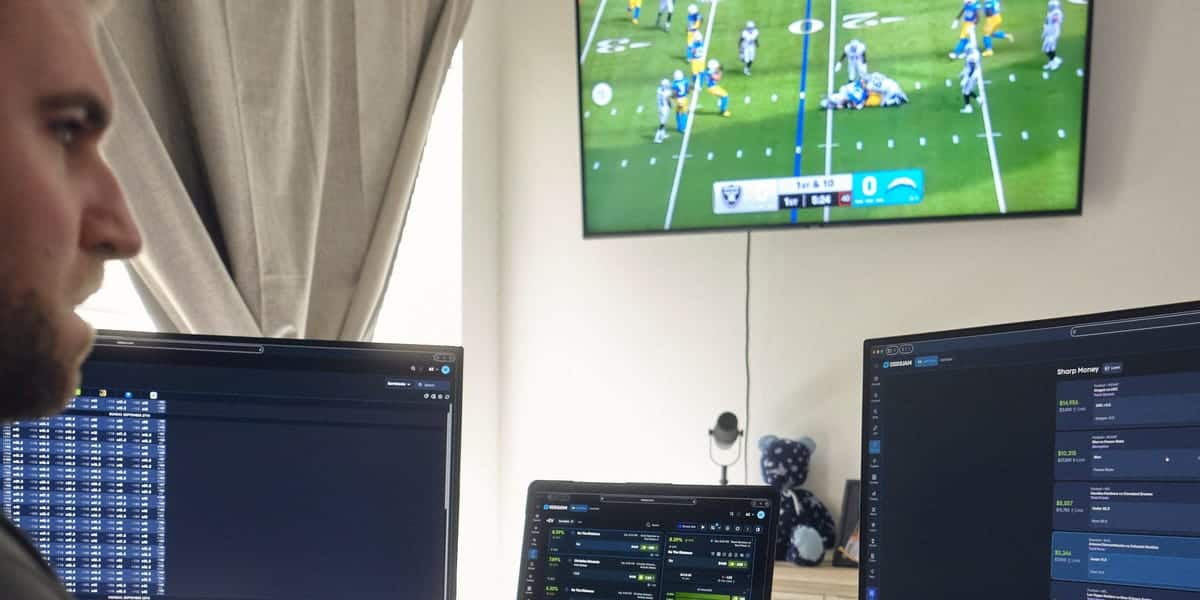
Bill Collins, who previously struggled with gambling addiction, now makes a living through sports betting, viewing it as a disciplined strategy rather than a form of gambling. He reported a profit of $12,656 in August, achieving a gain of over 8% on his wagers. Collins aims for daily compound returns of 3%-5%, believing this can outperform traditional investments like the S&P 500.
The rise of app-based sportsbooks and prediction markets has led to increased participation in sports betting. Some individuals, particularly among Gen Z investors, are redirecting funds into these platforms, with a significant portion viewing sports betting as a long-term investment strategy or a way to accelerate financial goals. According to a Betterment survey, over half of Gen Z investors have moved funds into sports betting, and 26% consider it an investment strategy.
The US sports betting industry has seen substantial growth since the Supreme Court overturned a federal ban in 2018, now valued at $17 billion, a 4,150% increase from $400 million. Collins, inspired by influencers like Alex Monahan who discussed arbitrage strategies, returned to sports betting in 2021. Arbitrage, a trading tactic involving betting on all outcomes of a game across different sportsbooks to profit from price discrepancies, is a key strategy he employs. Collins dedicates half his day to betting and the other half to creating content about sports betting strategies, describing arbitrage as an "almost zero risk" approach when understood mathematically.
Collins asserts that his current approach removes the emotional and uncertain elements that made gambling addictive in his youth. He acknowledges a lingering stigma, with family members expressing concern. However, he finds discipline and consistent account growth to be a compelling reason to continue. This approach reflects a shift for some younger individuals seeking alternative paths to financial independence amid stagnant wage growth and rising costs of living.